

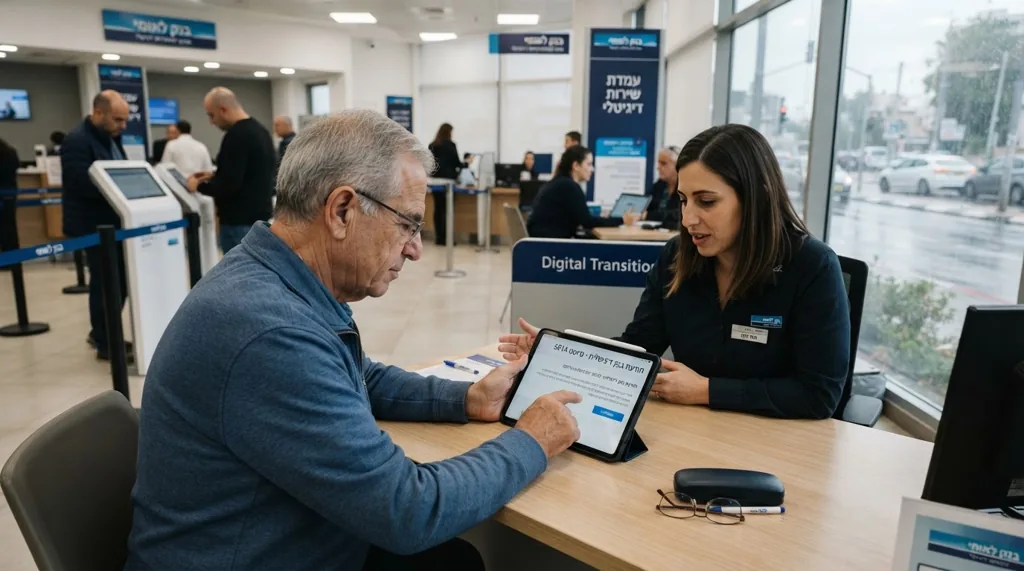
Israel’s bank supervisor drafted rules letting banks send notices digitally without consent, but not to customers aged 70 or older.
The Bank of Israel’s Banking Supervision Department has drafted rules that would let banks send customer notices digitally without first asking for consent. Customers aged 70 or older, and people who have not used online banking for a year, could not be switched without their consent.
The draft circular is dated 3 November 2026 and is addressed to Israel’s banking corporations1. It would repeal Directive 420, the current rule on sending notices by electronic means, and replace it with a new Directive 501A titled "Sending notices to customers"1. The draft states no comment deadline, and the changes would take effect on the date the final circular is published1.
| At a glance | Details |
|---|---|
| What was published | Draft circular from the Supervisor of Banks |
| Published on | 3 November 2026 |
| Who must comply | Banking corporations in Israel |
| Feedback deadline / Effective date | No deadline stated; effective on final publication |
| Final rules / Next milestone | Publication of the final circular and Directive 501A |
Why the Bank of Israel wants digital notices by default
Under current rules, physical mail is the default for notices to customers. A bank may send notices digitally only after the customer asks to join that service1. The draft would remove this regulatory barrier, so banks could send notices digitally on their own initiative1.
The department lists the expected benefits. Customers would get information about account activity close to when it happens1. They could also save, print and forward notices more easily. The draft also points to environmental protection, efficiency and better access for customers living abroad1.
The change is optional for banks. The draft says it does not force any bank to send digital notices to customers who did not ask for them1. Each bank may decide for itself, subject to the conditions in Directive 501A.
What Directive 501A changes for banks
The draft replaces Directive 420 because the changes are large in scope1. Some parts of the old directive still apply and move across into Directive 501A1. The Supervisor of Banks made the decision after consulting the Advisory Committee on Banking Business and with the Governor’s approval1.
| Area | What the draft requires |
|---|---|
| Bank policy | Each bank must set a written policy on which customer groups it switches1 |
| Notice channels | Banks match each type of notice to a suitable channel1 |
| Links in messages | Replaced by telling customers where to find the notice, due to link-based fraud1 |
| Joint accounts | Each account holder must receive notices1 |
| Contact details | Banks must offer customers a way to update details remotely1 |
A related directive on online banking, Directive 367, is also updated. The draft deletes its requirement for a customer’s explicit consent to join digital notices1. The consumer disclosure rules, the Banking (Customer Service) Rules of 1992, are amended to match1.
Who is protected from the switch
The draft sets consumer protections for groups that a bank wants to move from paper to digital mail1. Banks must study customer characteristics and needs, using tools such as satisfaction scores, surveys and behaviour analysis1.
Safeguards before a bank switches customers
| Requirement | Standard / Details |
|---|---|
| Age limit | No bank-led switch for customers 70 or older |
| Inactive users | No switch after a year without website or app use |
| Contact details | Checked as current before the switch |
| Customer notice | Told of the change and the right to paper mail |
Two groups cannot be switched by a bank on its own initiative:
- customers who are 70 or older at the time of the switch1
- customers who have not used the bank’s website or app for a year1
A customer aged 70 or older who already gets digital notices can keep receiving them1. Banks must also check that contact details are current before a switch. They must tell customers about the change and about their right to return to physical mail1.
How the six-month check works
Banks must monitor whether customers actually read their digital notices1. If a bank has no sign that a customer has viewed notices for six consecutive months, it must send a first notice. That notice goes through an instant channel, such as text message, and also by physical mail1.
When digital notices go unread
For customers switched by the bank, the notice must add a warning. If they ignore digital notices for six more months, the bank will return to physical mail1. If there is still no sign of engagement, the bank must make a reasonable effort to contact the customer for instructions1.
This builds on older rules. A 2018 amendment to Directive 420 already required notices by another channel for customers who had not used a service for nine months2.
How the old and new rules compare
The draft also cancels Supervisor of Banks circular 2528-06 from 2017, on accounts that need no customer signature1. Most of its sections are no longer needed under the Electronic Signature Law of 20011. The rest move into Directive 367. The new rules will be reviewed after 10 years under Israel’s 2021 regulation principles law1.
Key terms in plain words
| Term | Meaning |
|---|---|
| Supervisor of Banks | The Bank of Israel official who oversees Israel’s banks |
| Directive 420 | The current rule on how banks send notices electronically |
| Directive 501A | The proposed new rule on sending notices to customers |
| Physical mail | Paper letters sent by post |
| Digital mail | Notices sent through the bank’s website, app or text message |
| Opt out | A customer’s right to return to paper notices at any time |
The rules would take effect on the date the Supervisor of Banks publishes the final circular1.
Sources
- ↩ ירושלים, ל’ כסלו תשס"ז https://www.boi.org.il/media/ywlh5uvp/111615.pdf
- ↩ Microsoft Word – Circular 2550 – Jan 2018 – Dir 420.docx https://www.boi.org.il/media/ebqga2b0/h2550-en.pdf